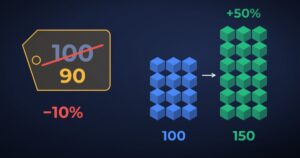
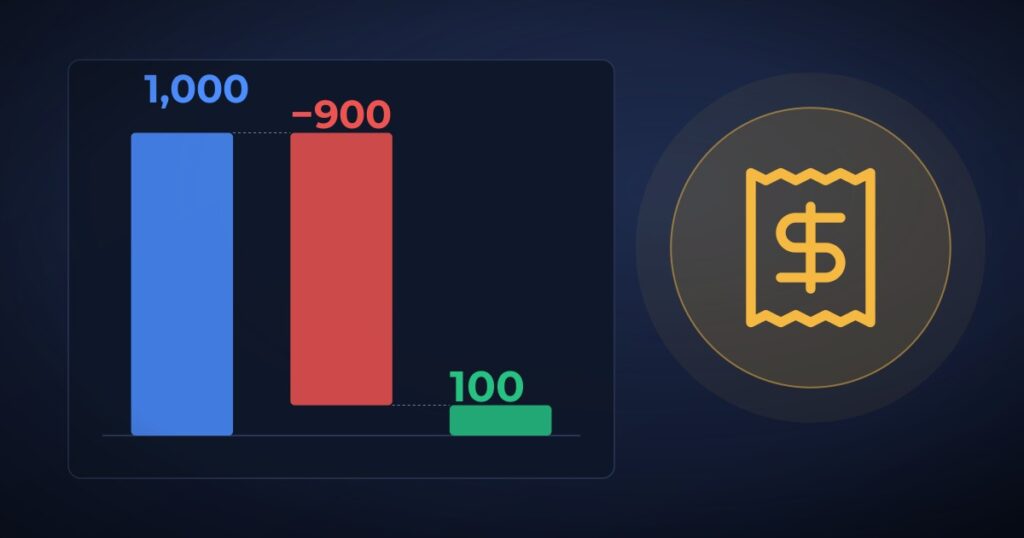
An invoice attracts attention because of its size. What remains from it helps explain the decision. Deduct discounts, returns, and the variable costs associated with the sale, including service and delivery where applicable.
In a hypothetical example, revenue of 1,000 with variable costs of 900 leaves a contribution of 100 before fixed costs. A smaller transaction could leave more if it consumes fewer resources.
Define the costs consistently, then consider contribution alongside time and risk. Volume matters, but it cannot by itself identify the work that best supports the business.
فاتورة كبيرة وربح صغير
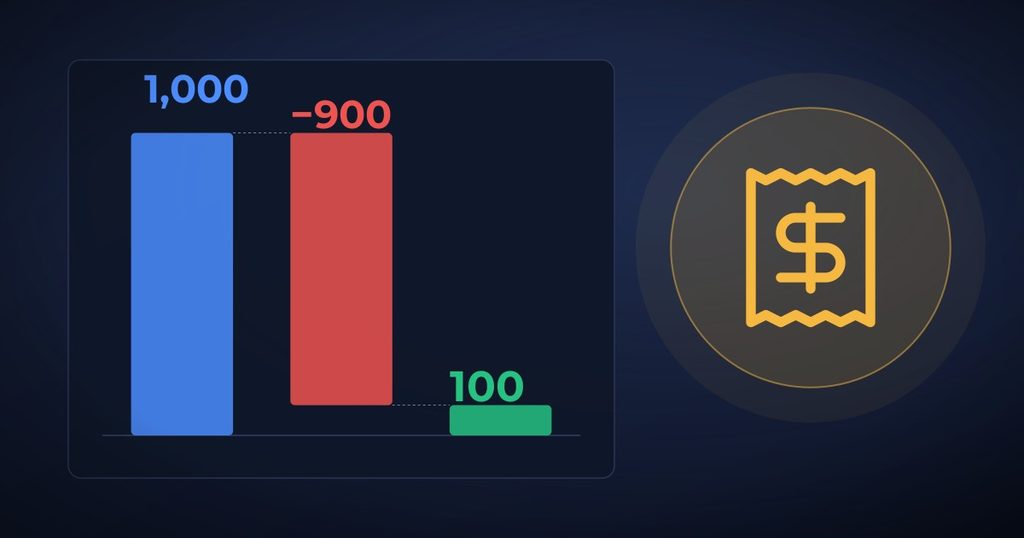
قيمة الفاتورة تلفت النظر، لكن ما يبقى منها هو الذي يساعد على فهم القرار. اطرح الخصومات والمرتجعات والتكاليف المتغيرة المرتبطة بالبيع، بما فيها الخدمة والتوصيل حيث تنطبق.
في مثال افتراضي، بيع بقيمة ألف وتكاليف متغيرة قدرها تسعمائة يترك مساهمة مائة قبل التكاليف الثابتة. صفقة أصغر قد تترك أكثر إذا كانت أقل استهلاكًا للموارد.
احرص على تعريف التكاليف المستخدمة في المقارنة. ثم قيّم المساهمة والوقت والمخاطرة معًا. الحجم مهم، لكنه لا يخبرنا وحده أي الأعمال يجعل الشركة أقدر على الاستمرار.